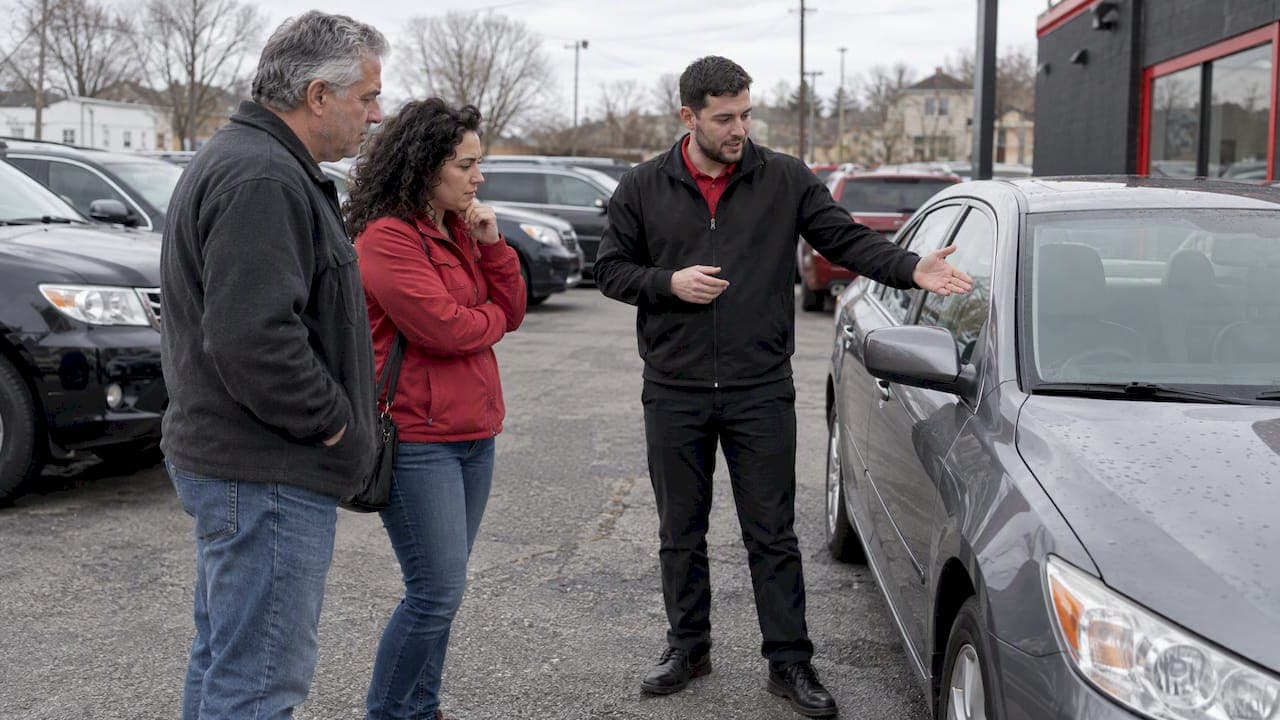
Yes, you can get a car loan after bankruptcy, and most people do find financing again. What changes is the timing and the terms: Chapter 13 filers generally need trustee or court approval before taking on new debt, while Chapter 7 filers often see offers once their case discharges. Expect higher interest rates and a down payment in the 10-20% range, or a cosigner to improve your terms.
TL;DR:
- Chapter 7 applicants often qualify after discharge, while Chapter 13 borrowers need trustee or court approval before borrowing during their three to five year plan.
- Expect a 10% to 20% down payment; a cosigner or established bank relationship may improve terms, while specialty lenders often charge higher rates.
- Compare preapprovals from at least two lenders, bring the strongest written offer to the dealership, and budget for insurance, registration, and routine maintenance.
- Before signing, verify the full APR, itemized fees, optional product costs, and credit bureau reporting; walk away if the dealer withholds details or applies pressure.
- After 12 to 18 months of consistent payments, compare refinance offers; confirm the original lender reports payments to all three major credit bureaus.
Table of Contents
- How Chapter 7 and Chapter 13 affect when and how you can finance a car
- Where to look for financing and what lenders typically require after bankruptcy
- Practical preparation checklist: documents, credit fixes, and getting preapproved
- How to spot and avoid predatory financing, add-ons, and payment traps
- Rebuilding credit and refinancing after a post-bankruptcy loan
- How Elmwood Auto Sales supports buyers rebuilding credit
- What actually matters when rebuilding your auto financing after bankruptcy
- Ready to apply? Here's how to start with Elmwood
- FAQ
- Sources
How Chapter 7 and Chapter 13 affect when and how you can finance a car
The two bankruptcy types follow different clocks. A Chapter 7 case often wraps up within several months, and discharge typically follows the 341 meeting of creditors by about 60 to 90 days. Many lenders will consider an application once that discharge is final, since your eligible unsecured debts are then resolved.
Chapter 13 works differently because you are still inside an active repayment plan, which typically runs three to five years. Taking on a new auto loan during that window generally requires permission from the bankruptcy trustee or the court, since new debt affects your ability to complete the plan. The process varies by jurisdiction, but trustees commonly want proof of the vehicle's necessity, the proposed loan terms, and how the new payment fits your budget.

If your current car fails and you need one urgently, this kind of request can move forward, but talk to your bankruptcy attorney first, and consider options like buy-now-pay-later for car parts to manage additional vehicle needs. Filing for approval incorrectly, or skipping it, can jeopardize your case.
Where to look for financing and what lenders typically require after bankruptcy
Not every lender treats bankruptcy the same way, so it pays to know your channels before you start shopping.
- Credit unions often offer more flexible underwriting and lower rates for members with recent bankruptcy history.
- Community banks may extend reasonable terms if you already hold an account with a steady deposit history.
- Specialty or subprime lenders focus on post-bankruptcy borrowers but usually charge higher APRs in exchange for approval.
- Dealer indirect financing connects you to a network of lenders through the dealership, which can save time comparing offers.
- Buy-here-pay-here dealers approve almost anyone but may not report payments to credit bureaus, so confirm that in writing if rebuilding credit matters to you.
A down payment of 10-20% is commonly recommended for post-bankruptcy borrowers, since it lowers the lender's risk and can meaningfully reduce your interest rate.
Lenders will weigh your income, debt-to-income ratio, and the size of your down payment alongside the collateral value of the car itself. A cosigner with solid credit, or a long-standing relationship with your bank or credit union, can shift an offer from merely approved to genuinely affordable.
Practical preparation checklist: documents, credit fixes, and getting preapproved
A little preparation before you walk into a dealership changes the entire negotiation. Work through these steps in order:
- Pull your credit reports at AnnualCreditReport.com and dispute any errors, including confirming that discharged bankruptcy accounts show a zero balance.
- Build a monthly budget that includes insurance, registration, and routine maintenance, then set a conservative payment target before you shop.
- Save a meaningful down payment and gather proof of steady income along with current residence documentation.
- Get prequalified or preapproved from at least two lenders, credit unions are a strong starting point. You can compare real offers rather than dealer quotes alone.
- Bring your written preapproval into any negotiation; it gives you leverage and a clear benchmark for the dealer to beat.
- If a cosigner is part of your plan, have an honest conversation about what happens to their credit if a payment is missed.
Pro Tip: Treat your preapproval letter as your walk-away number: if the dealer's financing can't match or beat it, you already have a better deal in hand.
How to spot and avoid predatory financing, add-ons, and payment traps
The FTC has documented recurring harms in dealer financing, including payment packing, vague "as low as" APR advertising, and add-ons slipped into the contract without clear disclosure. Post-bankruptcy buyers are often targeted precisely because they expect to be turned away and accept the first offer out of relief.
Before signing anything, ask the finance manager for:
- The full APR, not just the advertised monthly payment.
- The total amount financed, including every fee itemized separately.
- A written list of every add-on product and its individual cost.
- Confirmation, in writing, of whether payments will be reported to the credit bureaus.
If the finance office resists giving straight answers to any of these, or pressures you to decide on the spot, that is your signal to walk away and shop elsewhere. A longer piece on common financing mistakes buyers make covers more of these warning signs in detail.
Rebuilding credit and refinancing after a post-bankruptcy loan
A post-bankruptcy auto loan is rarely your last stop. It is often the quickest route back to a stronger credit file, since on-time installment payments report monthly and carry real weight in scoring models.
- Pair your auto loan with a secured credit card or a credit-builder loan to diversify your credit mix.
- Confirm your lender reports to all three major bureaus, since this is where buy-here-pay-here arrangements often fall short.
- Track your score every few months and start shopping to refinance once it climbs meaningfully, typically after 12 to 18 months of consistent payments.
Refinancing at that point can lower your rate and your monthly payment without changing the car you already drive.
How Elmwood Auto Sales supports buyers rebuilding credit
We have financing programs designed around the reality that bankruptcy does not define your ability to handle a car payment responsibly. Our tailored options work with a range of credit histories rather than screening buyers out at the first sign of a discharge or a repossession.
Every vehicle offered passes a thorough inspection before it reaches the lot, so the payment you commit to is not followed by a surprise repair bill. If you are ready to see what financing looks like for your situation, our bad credit car buying guide and our explanation of guaranteed auto loans for bankruptcy recovery are good next reads.
What actually matters when rebuilding your auto financing after bankruptcy
The conventional advice tells people to wait a year, fix their credit, then buy a car. In practice, the bigger risk is not timing, it is accepting the first approval without reading what is inside it.

What gets underweighted is the paperwork step: confirming your discharge is final, or that your trustee has actually signed off, before you let a dealer run your credit. Skipping that sequence causes more post-bankruptcy financing headaches than a low credit score ever does.
If you take one thing from this, prioritize comparing two real preapproval offers over chasing the fastest yes. Speed without comparison is how predatory terms slip through.
— Elmwood
Ready to apply? Here's how to start with Elmwood
Getting started is straightforward. Have your discharge paperwork or trustee approval letter, a valid ID, proof of income, and documentation of your down payment ready before you apply.
- Fill out our online financing application in a few minutes from home.
- Use our Car Finder tool to match your budget and preapproval to the right vehicle.
- Call our team to talk through your situation and get a preapproval estimate before you visit.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
How long does it take to get a 700 credit score after Chapter 7?
There is no fixed timeline since it depends on your payment history and how much debt you carry after discharge. Consistent on-time payments on an auto loan or secured card, combined with low balances, are the fastest documented path back to a stronger score.
Can I finance a car while in Chapter 13 bankruptcy?
Yes, but you generally need permission from your bankruptcy trustee or the court before taking on new debt during an active Chapter 13 plan. Talk to your bankruptcy attorney first, since the approval process and required documentation vary by jurisdiction.
What debt cannot be erased in bankruptcy?
Certain debts typically survive both Chapter 7 and Chapter 13, including most student loans, recent tax obligations, child support, and alimony. A bankruptcy attorney can confirm exactly which of your debts qualify for discharge based on your case.
What is the $3,000 rule for buying cars?
This is not an official regulation, and definitions of it vary across sources, so treat any specific number you see online with caution. If you come across this term, confirm its meaning directly with a lender or dealer rather than assuming a fixed rule applies to your purchase.
Sources
- How to get a car loan while in Chapter 13 | Steiner Law Group
- Can you finance a car after bankruptcy? | TheCreditPeople
- Combating auto retail scams (FTC report)
- Chapter 7 bankruptcy basics | U.S. Courts